All Categories
Featured


How Whole Life Insurance Works
1 Investopedia - How Whole Life Insurance Works. Updated May 7, 2025. . Accessed June 18, 2026. 2 Thrivent Whole life insurance coverage: Pros, cons & who it's best for. Updated March 10, 2026. . Accessed June 18, 2026. 3 Forbes - What Is Whole Life Insurance Coverage? (& How Does it Work?) Updated December 18, 2024.
Accessed June 18, 2026. 4 Forbes - What Varies Life Insurance Coverage? Upgraded November 26, 2024. . Accessed June 18, 2026. Content within this short article is offered general informational functions and is not supplied as tax, legal, health, or monetary suggestions for any individual or for any specific circumstance.
For total information, consisting of schedule and expenses of Aflac insurance coverage, please call your regional Aflac agent/producer. Aflac life plans A68000 series/Term Life: In Arkansas, Idaho, Oklahoma, Oregon, Texas, Pennsylvania & Virginia, Policies: ICC1368200, ICC1368300, ICC1368400. In Delaware, Policies A68200, A68300 & A68400. In New York, Policies NY68200, NY68300 and NY68400.
Life Insurance for Service Members
In Delaware, Policy A68100. B60000/Term Life: In Arkansas, Oklahoma, Pennsylvania, Texas & Virginia, Policies ICC18B60200, ICC18B60300, & ICC18B60400. Whole Life: In Arkansas, Oklahoma, Pennsylvania, Texas & Virginia, Policies: ICC18B60C10, ICC18B60100.
In Delaware, Policy Q60200M. In New York, Policy: NYQ60200M. Not available in Virginia. Whole Life: In Arkansas, Delaware & Oregon Policy Q60100M. In Idaho, Policy Q60100MID. In Oklahoma, Policy Q60100MOK. In New York, Policy: NYQ60100M. Not readily available in Virginia. In AR, DE, ID, OK and VA: Policies ICC21-AFLLBL21 and ICC21-AFLRPL21; and Riders ICC21-AFLABR22, ICC21-AFLADB22, and ICC21-AFLCDR22.

In this article, we explain what entire life insurance coverage is and compare it to term life insurance, as well as universal life and variable life insurance. Entire life insurance is one kind of permanent insurance and is extremely various from term life insurance, which provides coverage for a given duration only and does not construct money value. If term life insurance is the most common form of life insurance coverage, entire life insurance coverage is the oldest type of irreversible life insurance coverage.
Covered California Special EnrollmentThe larger your cash worth, the larger the loan you can take. You can utilize your money worth to supplement your other retirement earnings. Entire life insurance coverage is the only kind of life insurance that ensures of the following: The death benefit won't decrease The policy won't end as long as premiums are paid Your premiums will not
Covered California Special Enrollment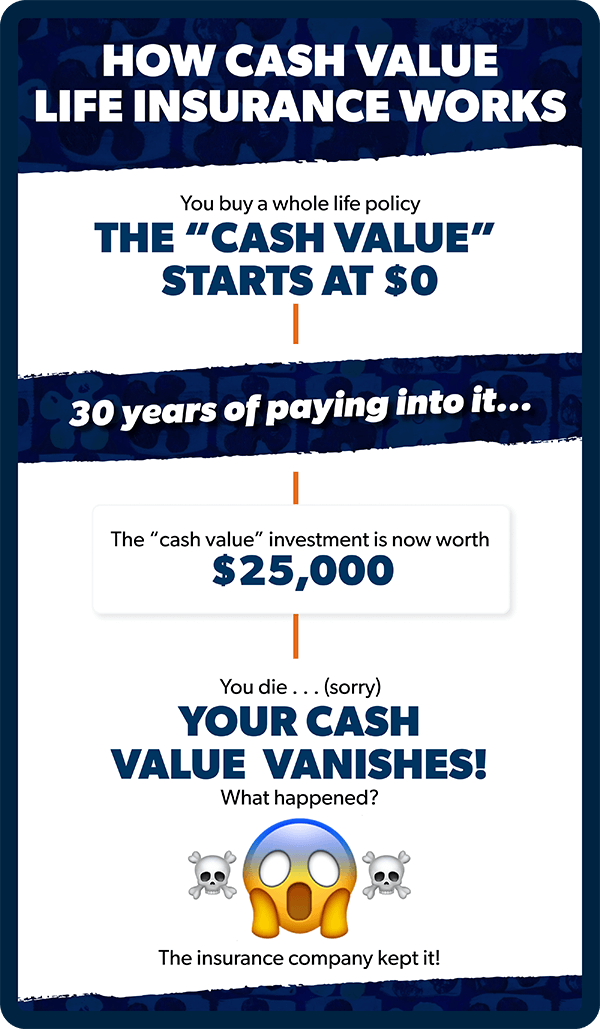
increase Your expenses will never ever increase The insurer ensures that the cash worth of your whole life insurance coverage policy will grow with time. figure out how much your cash worth need to grow based on existing rate of interest, which, naturally, differ in time. allow you to invest funds in policy subaccounts, similar to shared funds. Your money value will increase orreduce, depending upon the efficiency of these subaccounts. What occurs if performance of the money value of your universal or variable life policy drops? Who needs to ante up more superior to keep your policy in force? You do. Neither choice is excellent. If you have an entire life policy, you will not need to make those awful choices. The premium, money worth, and death benefit are all ensured. And did you understand you can find out precisely what your guaranteed premium, money value and survivor benefit will be at any moment before you choose if it makes good sense to start an entire life policy? Just ask for a FREE, no-obligation Analysis here to take the initial step. In a manner, it's like getting an income tax refund. Now, dividends are not ensured. It's imaginable an insurance coverage company could have a terrible, dreadful, no great, very bad year . That's what the business plans for. And every year that'smuch better than they prepared, they can pay a dividend. Get Your FREE Report! Get immediate access to the FREE 18-page Unique Report that reveals how super-charged dividend paying whole life insurance lets you bypass Wall Street, fire your lender, and take control of your financial future. You get to inform the insurance coverage business what to do with your dividend. and this simply might be the neatest thing since cupcakesyou can have them use your dividend to purchase more insurance coverage for you insurance you'll never ever have to pay another premium for once again. Think of that! You can buy extra insurance that's paid up, implying no more premiums will be due on that additionever. If that reminds you of the eighth wonder of the worldcompound interestthat's due to the fact that the idea is exactly the very same. Just paid up entire life insurance coverage additions construct both your policy's money value and your death benefit. You can find out more here about dividend-paying whole life insurance coverage, which many individuals discover particularly amazing. Term life insurance coverage premiums go upsometimes drasticallywith every new term, because much of the cost of insurance is based on how likely you are to die at a given age, and as you grow older, that possibility increases. Universal and variable insurance premiums can go up, tooagain, sometimes drasticallyif money worth drops dueto low rates of interest or poor investment performance. So you may be asking, "If it costs more to insure my life with every death year, how can a life insurance company promise my premiums will never increase?" The response is elegantly simpleand it assists discuss why entire life insurance is more costly than term insurance in the early years of the policy.

Latest Posts
Understanding US Medicare Enrollment Options and Seniors

Protecting Financial Wealth with Whole Life Insurance
Securing Coverage to Support Families