All Categories
Featured

Securing Coverage to Support Families
Table of Contents
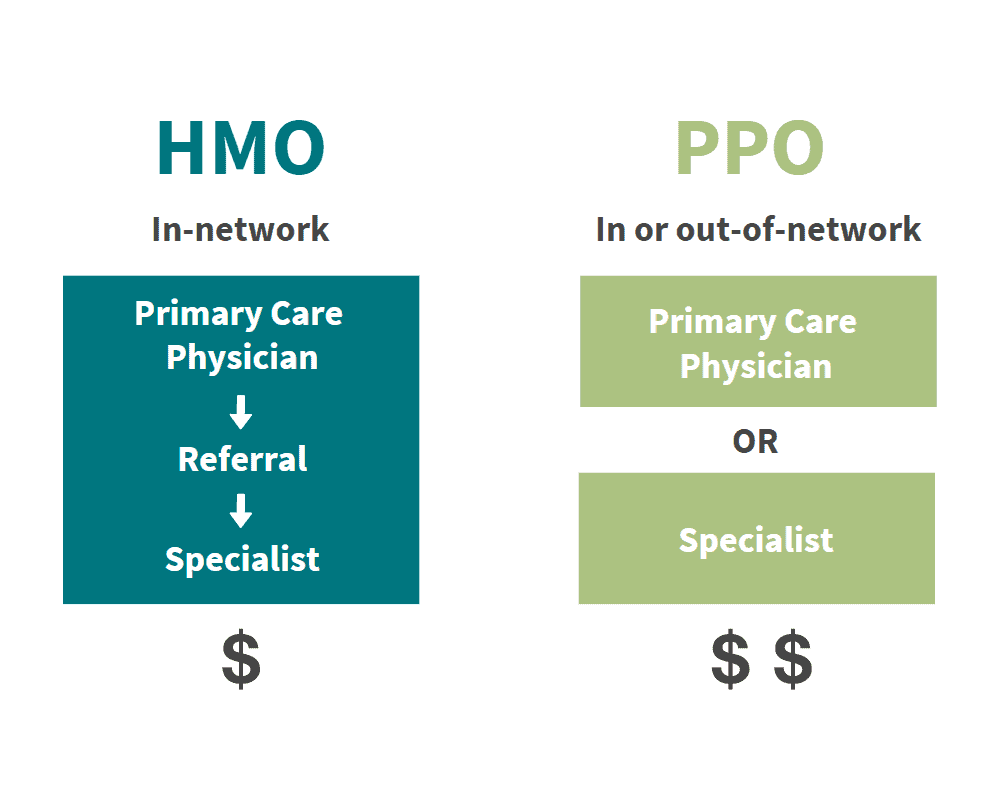
An HMO Medicare Advantage strategy supplies a network (referred to as an "HMO network") of healthcare providers and healthcare facilities to its customers. It's required for a client to choose a medical care physician to handle their health care and supply recommendations to any service providers that are not in the plan's network, except in case of an emergency situation.
The ease of having a primary care physician to coordinate and manage the care supplied. A client can just see service providers within the plan's network unless they have a recommendation for an outside specialist, or it's an emergency situation.
Unlike an HMO plan, a PPO Medicare Advantage strategy permits for more versatility when seeing out-of-network companies. It's not required to have a referral to see an out-of-network expert although it might be more costly and take extra time to get insurance coverage considering that a client need to submit a claim for protection each time they see an out-of-network service provider.
The client has more flexibility with which suppliers they select to see, whether they're within the strategy's network or out-of-network. A lot of times, there is no need for a recommendation if a client cares to see an out-of-network professional. Greater month-to-month premium. Most most likely, higher regular monthly premiums. The patient is accountable for handling their health care instead of a medical care company.
An EPO insurance coverage strategy, or an 'Special Company Organization' insurance coverage plan, is typically called a plan that is "situated in between an HMO and PPO." This is because, like a PPO plan, an EPO does not require a patient to stay in-network for care significance, no referrals or emergency situations are required for seeing an out-of-network supplier.
Insurance in Garden Grove CANavigating US Medicare Benefit Options and Seniors
This plan is less widely understood, it often provides a much bigger network than an HMO.A POS insurance strategy, or a 'Point of Service' insurance strategy, is also known to "mix aspects of HMO and PPO plans." This is because, like an HMO plan, a POS insurance coverage strategy requires a client to have a medical care medical professional that handles their health care and gives them recommendations to out-of-network experts or providers.
The Medicaid program provides Americans with low to no cost healthcare to individuals/households that have restricted income or impairments. Alongside Medicaid is a program understood as CHIP or 'Kid's Health Insurance Program,' which is a state moneyed program where clients pay low to no charge health care for kids and pregnant women who have actually restricted income.
According to the IRS, the deductible is at least $1,400 for a private and $2,800 for a family. In order to fight the high deductible expense, it is recommended that a patient contributes to an HSA/HRA or a 'Health Savings Account'/'Health Repayment Arrangement,' which companies often contribute to every year.
Another element to note about this plan is that it protects the patient from "catastrophic out-of-pocket costs for covered services." What this suggests is that, once a patient's "annual out-of-pocket expenditures for covered services from in-network providers, consisting of deductibles, copayments, and coinsurance, reaches the fixed devastating limitation," the insurance provider will cover all expenses.
HMO and PPO strategies share specific features. Both use a broad network of providers to pick from, both deal emergency situation care protection throughout the United States, and both generally include protection for prescription drugs. There are some main differences between HMO and PPO strategies. HMO plans require members to pick an in-network PCP to assist manage their care and supply recommendations.
Evaluating PPO and HMO Insurance
HMOs will not cover care from an out-of-network service provider. PPOs will, however you'll likely conserve when you remain in network. Finally, HMOs typically have lower premiums and out-of-pocket costs. PPOs may cost more, but they provide more flexibility.
When it comes to health insurance, you have your choice of a number of strategy types. Differences between HMO (Health Maintenance Organization) and PPO (Preferred Provider Company) strategies include network size, ability to see professionals, costs, and out-of-network protection.
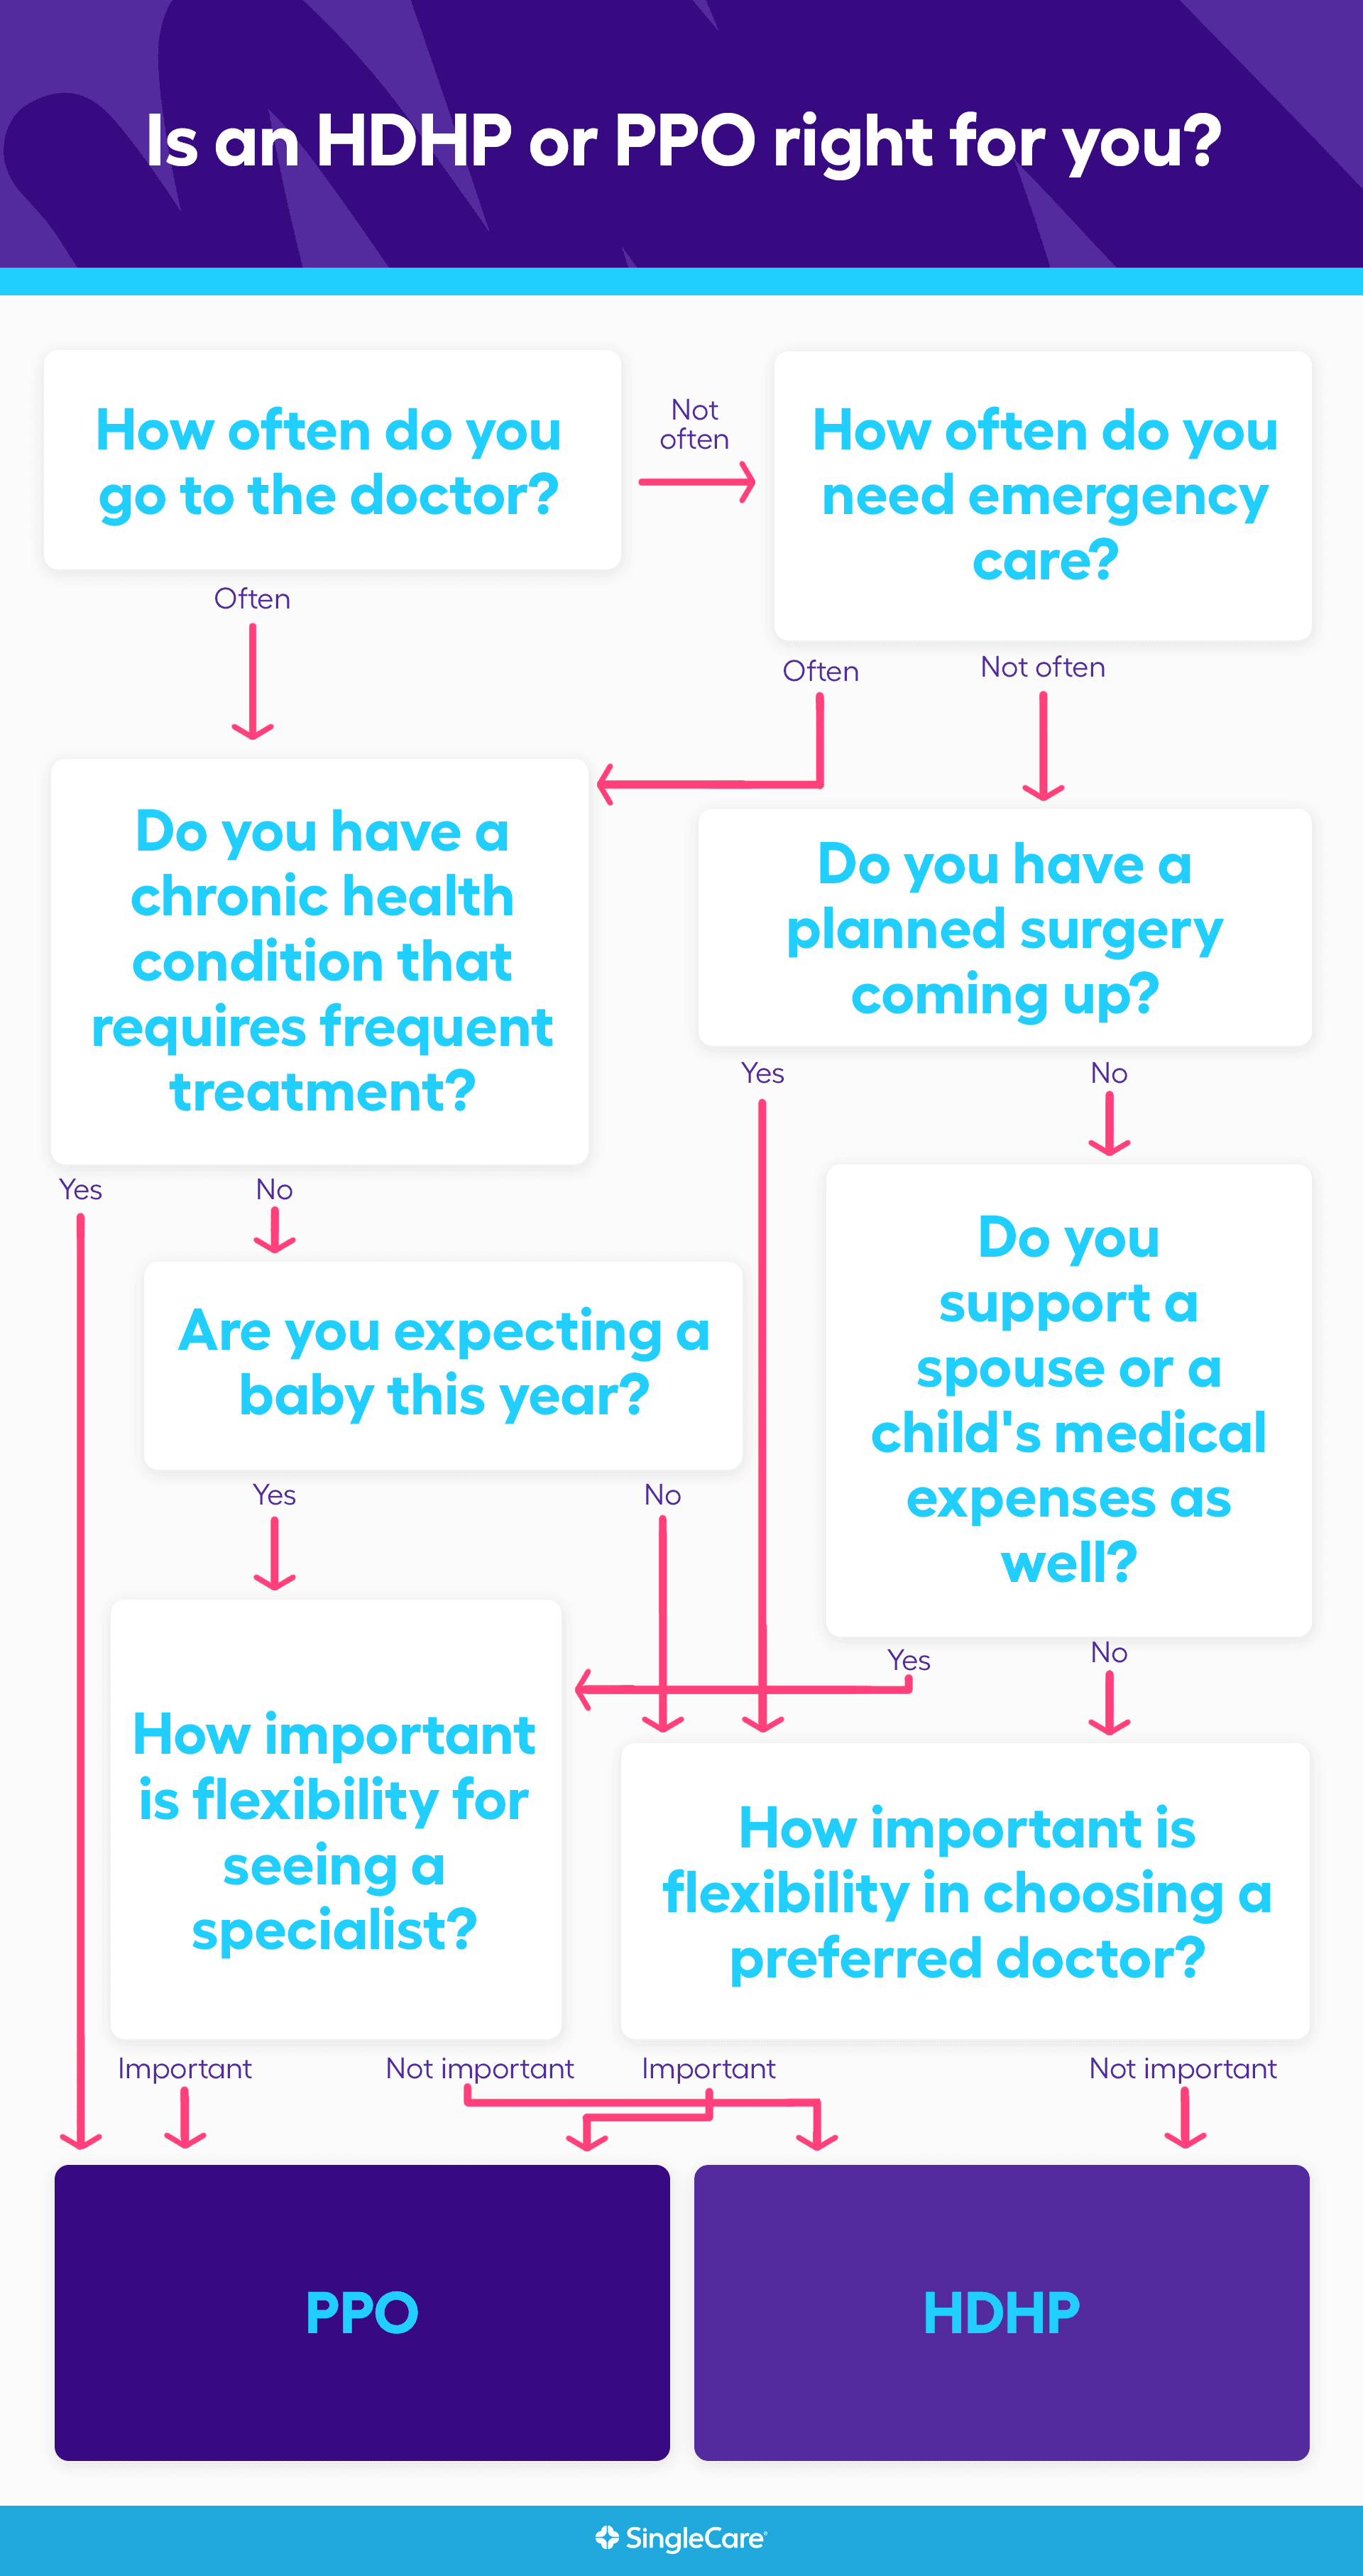
An HMO gives you access to specific medical professionals and healthcare facilities within its network. A network is comprised of suppliers that have actually agreed to reduce their rates for plan members and also fulfill quality requirements. But unlike PPO strategies, care under an HMO plan is covered just if you see a service provider within that HMO's network.

Latest Posts

Protecting Financial Wealth with Whole Life Insurance
Securing Coverage to Support Families

Securing the Individual Medical Insurance Quotes